Your loan is coming due. Run the math before your lender runs it for you.
An independent report that answers the four questions that matter when a small multifamily or commercial loan balloons: refinance, sell, 1031, or pay down. Built from your numbers. Nobody in it is selling you a loan, a listing, or an exchange.
$399. Delivered in 2 business days. Every report reviewed by a 30-year real estate and lending operator before it goes out.
Most owners find out the hard way.
Loans written in 2019 through 2022 are maturing into a market two to three points above the rate you have. Same building, same rents, and the new loan doesn't cover the old balance.
Three things owners are learning at the closing table:
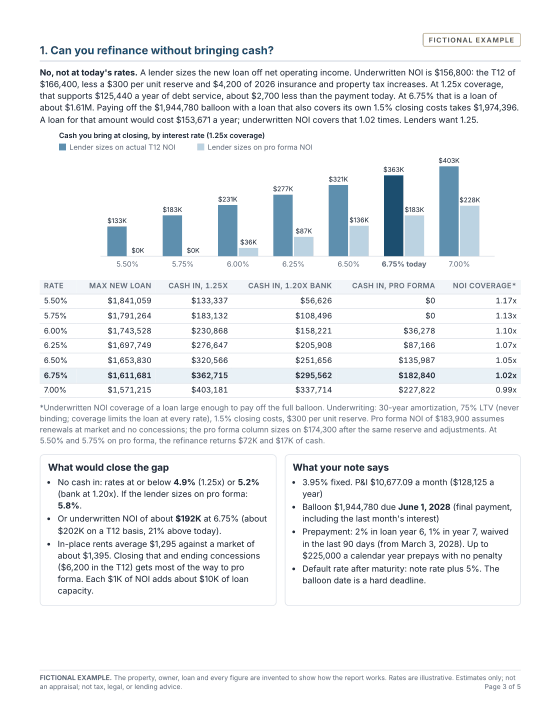
The refi needs cash. At a 1.25 DSCR and today's rates, a lot of properties support 10% to 25% less debt than they carry. That gap comes out of your pocket.
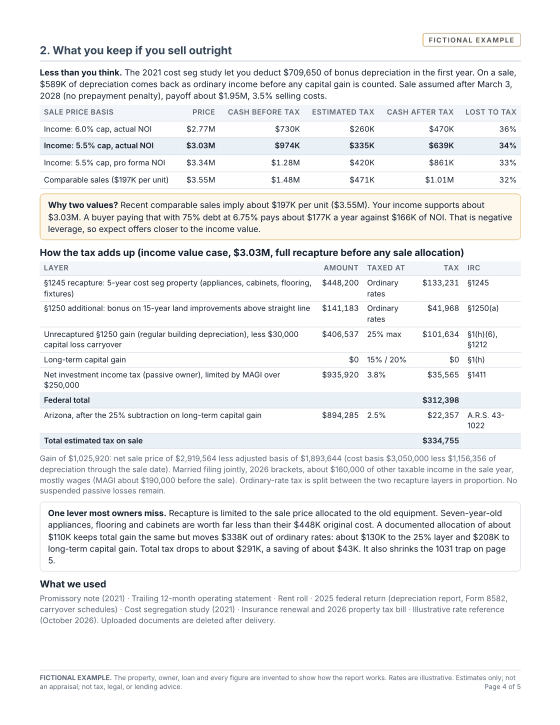
The tax on a sale is bigger than the gain. Depreciation recapture, especially after cost segregation or bonus depreciation, can take half or more of your sale cash. Most owners have never seen that number.
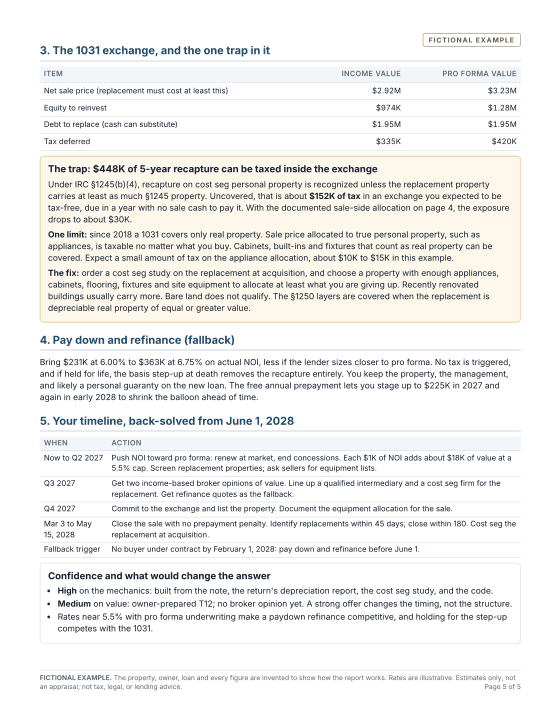
A 1031 doesn't defer everything. Personal property recapture from a cost seg study can still be taxable in an exchange. Your exchange company won't tell you that. It isn't their job.
Every free "sell or refi?" tool online comes from someone who gets paid when you pick their answer. This one doesn't.
Four questions. Real numbers. Your property.
1
Can I refinance without bringing cash?
If not, how much cash, at what rate, and what rate makes it work. Includes the new payment and what it does to your cash flow.
2
What is the property worth on its income?
Not comps. Income. That's what the lender and the buyer's lender will use. Shown as a range with the math visible.
3
What do I keep after tax if I sell?
Federal, state, recapture, net investment income tax, and any carryover losses you can use. Built from your return, not a rule of thumb.
4
What does a 1031 save, and what can it fail to save?
The deferral, the exposure that survives the exchange, and the timeline.
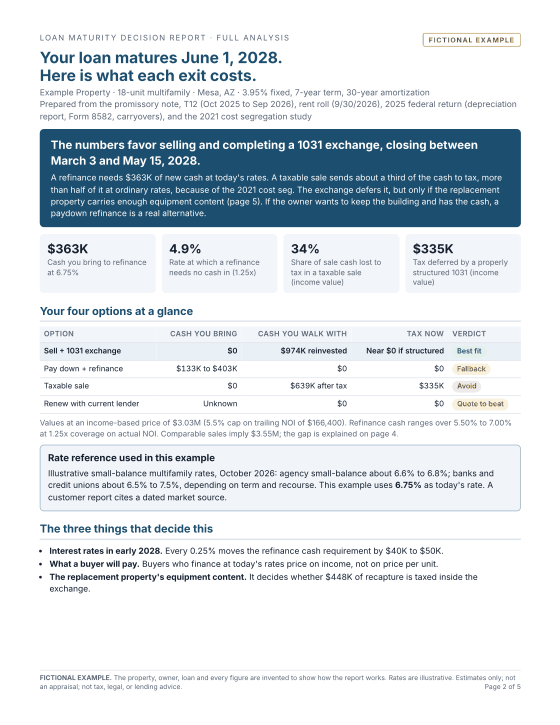
Then the numbers are laid side by side: refi, sell, 1031, pay down. The report tells you which one the numbers favor and why. The decision stays yours.
The sample report
Four pages from the sample. Fictional property, fictional numbers, real method.
About 45 minutes with your note, last return, rent roll and operating statements in front of you. It asks for figures, not documents; nothing is uploaded.
3
Get the report.
PDF by email within 2 business days. Reviewed by a person before it's sent.
That's it. No sales call, no follow-up pitch, no one asking to "hop on a quick call."
One report. $399. Here is what is in it.
The Maturity Math Report, $399
Refi sizing and cash-to-close
Income value range
Full sale tax build from your return, including recapture by type, state, NIIT and carryovers
1031 deferral plus the exposure that survives the exchange
Took cost segregation or bonus depreciation between 2018 and 2023? This report is built for you. The tax most owners estimate from their own books misses the recapture by six figures. On our own test property the miss was about $140,000.
We ran it on our own building first.
Twelve units in Phoenix. A 3.8% loan with a $1.77 million balloon in 2028. Here is what the report found, in order:
$400,000
Refinancing at today's rates needed roughly $400,000 in cash to close.
$600,000
The property's income value came in about $600,000 under what comps suggested.
62%
A taxable sale would have sent 62% of the cash to tax, mostly recapture from a cost segregation study.
Six figures
A 1031 deferred most of it, but still left a six-figure exposure the exchange couldn't fix.
The owner-books-only version of the report missed the tax by about $140,000. The version built from the return and the cost seg study caught it. That is why this report is built from your return.
Thirty years in real estate and lending. No license to protect, no product to sell.
MP
I'm Mark Pietramale. I spent 30 years as a loan originator, regional lending manager, Realtor, and investor. I own a 12-unit building in Phoenix with a loan that balloons in 2028. I built this report to make my own decision, then realized nobody sells an honest version of it to anyone else.
Every free analysis I could find comes from a lender, a broker, or an exchange company. They're not lying to you. They're just paid when you pick their answer.
This report has no lender names in it, no broker names, no exchange company names. We don't take referral fees. We don't originate loans or list property. The math is the whole product.
Questions owners ask.
Is this advice?
No. It's independent financial analysis built from the numbers you provide. It is not tax, legal, investment, or lending advice, and it is not an appraisal. Take it to your CPA, attorney, and lender. It will make those conversations shorter.
Who reviews the report?
A person. At launch, that's Mark. The math runs through a tested engine; a human checks every report before it's sent.
Is the report AI-assisted?
Yes. The analysis engine uses AI to run your figures against current tax code. Every output is checked by a person before delivery.
What happens to my documents?
You don't send us documents. The intake asks for figures from your note, return, rent roll and operating statements, and you type them in. Those entries are used to build your report and deleted 30 days after delivery. No Social Security numbers or account numbers are collected.
Can I fix a number after I submit?
Yes. One correction round within 7 days of delivery, through a link in your delivery email.
Do you recommend lenders, brokers, or exchange companies?
No. Never. Not in the report, not by email, not for a fee.
What if my situation is unusual?
Partnerships, multiple properties, mixed-use, seller financing, and prior exchanges are all fine. If we can't build a report from what you enter, you get a full refund.
How long does it take?
Two business days from the time we have complete inputs.
What states do you cover?
All 50. State tax is built into the sale analysis.
Refund policy?
Full refund if we cannot produce a report from your inputs. No refund after delivery.
Your maturity date is not a paperwork date. It's a forced decision on the biggest asset you own.